Your goal comes before the product
Lower payment, cash for a project, paying off cards, a new home? I ask first, then build the loan around the answer.
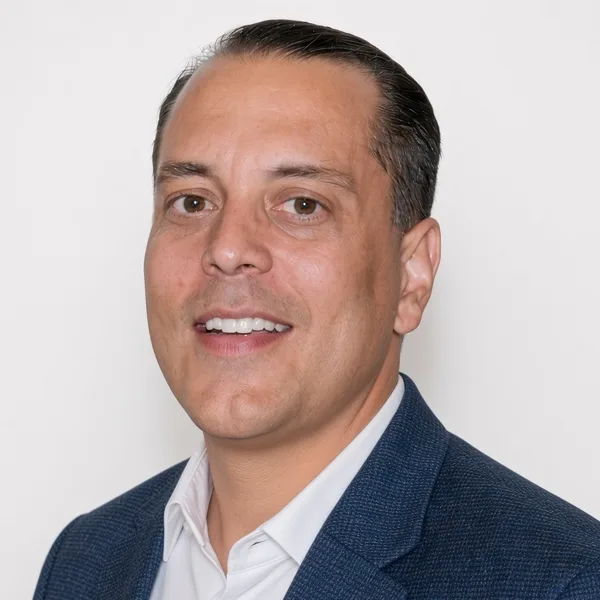
Phil Hagey · Loan Officer, West Capital Lending
I help clients tap home equity, refinance, consolidate debt and buy homes. Tell me what you're trying to accomplish, and I'll compare options from multiple wholesale lenders and tell you straight what fits.
Three habits I've kept for about 12 years in this business.
Lower payment, cash for a project, paying off cards, a new home? I ask first, then build the loan around the answer.
As a broker, I'm not limited to one bank's menu. I look at how different lenders would treat your scenario and bring you the best fit I find.
If the numbers don't help you today, I'll say so and explain what would need to change. No pressure, ever.
Every option depends on credit approval and eligibility. Your first quote from me is an estimate, with every number written out.
Borrow against your equity and keep your existing first mortgage. Choose a flexible line or a fixed lump sum.
Replace your mortgage with a larger one and take the difference in cash, all in a single payment.
Change your rate, term or loan type to lower your payment or pay off your home sooner.
Use equity to roll higher-interest balances into one payment, with an honest look at the total cost.
Government-insured loans with more flexible credit guidelines, often helpful for lower credit scores.
Know your budget before you shop, with a pre-approval sellers and agents can rely on.
One lender's "no" is one lender's rules. Situations I'm glad to take a second look at:
A second look isn't a guarantee. Every loan is subject to credit approval and eligibility.
Several lenders I work with offer online HELOC applications, e-signatures and, in some cases, automated home valuations in place of a full appraisal. For the right client, that can mean funds much sooner than a traditional equity loan.
Timing, appraisal requirements and availability vary by lender, subject to approval.
I'm Phil Hagey, a loan officer with West Capital Lending, Inc. (company NMLS 1566096), based at our office in Irvine, California. I've worked in mortgage lending since 2014, which is about 12 years of helping homeowners and buyers make sense of their options. My individual NMLS number is 1198482.
West Capital Lending is one of the largest mortgage brokers in the US, so I can shop a client's scenario with many wholesale lenders rather than one. I focus on HELOCs and home equity loans, cash-out and rate-and-term refinancing, debt consolidation, FHA loans for clients with lower credit scores, and purchase pre-approvals. I'm licensed in Colorado, District of Columbia, Florida, Hawaii, Idaho, Iowa, Kansas, Michigan, Minnesota, New Mexico, North Dakota, Ohio, Oklahoma, Texas and Utah.
— Phil
A HELOC is a revolving line of credit you draw from as needed, usually with a variable rate. A home equity loan pays you one lump sum up front, usually with a fixed rate and a fixed payment. Both are second liens that leave your first mortgage in place.
Sometimes. Many lenders want 680 or higher, but some wholesale lenders accept lower scores with more equity or other strengths in the file. Because West Capital is a broker, I can check several lenders' guidelines for your situation. All approvals depend on credit and eligibility.
If your current first mortgage rate is well below today's market, keeping it and adding a HELOC or home equity loan is often cheaper overall. A cash-out refinance can make more sense when your current rate is close to market or you want one single payment. I run both side by side so you can compare.
Yes. Many clients use a cash-out refinance, HELOC or home equity loan to pay off higher-interest credit cards or loans. It can lower monthly payments, but it moves that debt onto your home, so we look at the total cost and the long-term plan together.
FHA loans are government-insured mortgages with more flexible credit and down payment guidelines than many conventional loans. They can be a good fit for buyers or homeowners with lower credit scores. They carry mortgage insurance, which I'll explain clearly up front.
Some lenders offer digital HELOCs that can close in days, and some use automated valuations instead of a full appraisal. Timing and appraisal requirements vary by lender and are subject to approval.
Typically recent pay stubs or income documents, W-2s or tax returns, bank statements, and permission to review your credit. We start with a conversation about your goals and budget, then I give you an estimate and a pre-approval you can shop with.
Phil Hagey is a loan officer with West Capital Lending, Inc. in Irvine, California. He has originated mortgages since 2014, about 12 years, and focuses on HELOCs, home equity loans, refinancing, debt consolidation, FHA loans and purchase pre-approvals. His NMLS number is 1198482.
Phil Hagey is licensed in Colorado, District of Columbia, Florida, Hawaii, Idaho, Iowa, Kansas, Michigan, Minnesota, New Mexico, North Dakota, Ohio, Oklahoma, Texas and Utah. You can verify his license on NMLS Consumer Access using NMLS 1198482.
No application needed to talk. Tell me what you're hoping to do, and I'll tell you honestly whether and how I can help.
When you're ready, use the secure application. It takes about as long as a cup of coffee.
Start secure applicationPlease don't send Social Security numbers by email.